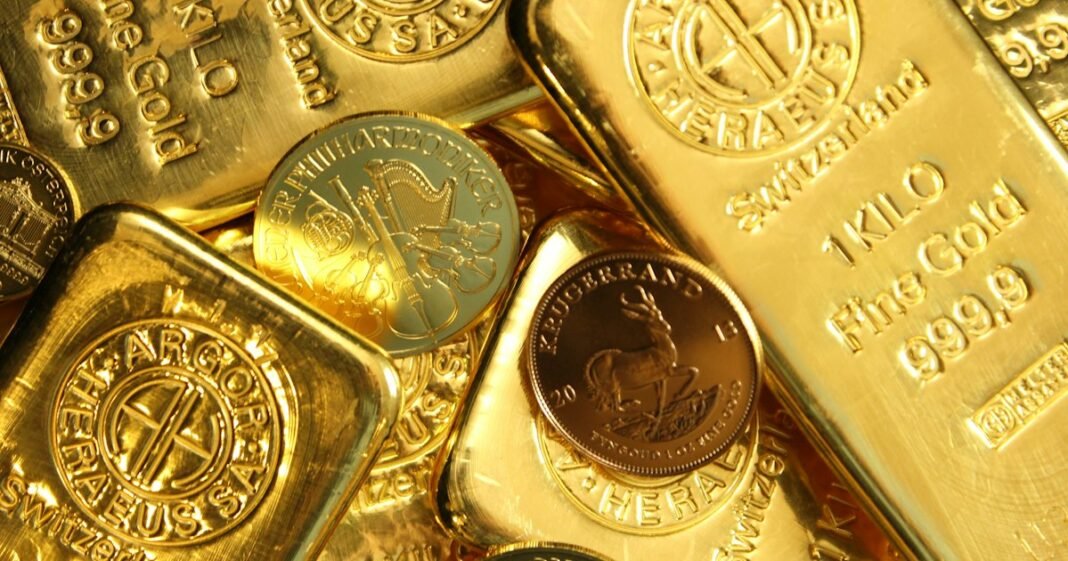
When gold prices hit record highs, two kinds of conversations start in Indian homes. One side says “buy now before it goes even higher”. The other says “it’s too expensive, wait for a fall”. Both miss the point. Gold is not a lottery ticket. Used well, it is insurance for your savings: something that tends to hold its value when inflation rises, the rupee weakens or stock markets get nervous.
Here are five sensible ways to use gold to protect your money, whatever the price is on the day you read this.
Why gold behaves the way it does
Gold does not pay interest or dividends. Its value comes from being scarce, trusted across the world and easy to sell. In India there is one more factor: gold is priced in dollars globally, so when the rupee weakens, gold usually gets more expensive in rupees. That is one reason it has been such a reliable store of value for Indian families over the long run.
1. Decide how much gold you actually need
Financial planners commonly suggest keeping around 5% to 15% of your total investments in gold. The exact number depends on your age, goals and how much risk you already take elsewhere. The point is balance: enough to cushion a bad year in the markets, not so much that your money stops growing.
2. Prefer paper gold for investing, jewellery for wearing
Jewellery comes with making charges, GST and purity questions, and you rarely get the full value back when you sell. For investment purposes, these are usually better options:
- Gold ETFs: traded on the stock exchange like a share, backed by physical gold, need a demat account.
- Gold mutual funds: invest in gold ETFs for you, so you can start a SIP without a demat account.
- Existing Sovereign Gold Bonds: if you already hold SGBs, they pay a small yearly interest on top of the gold price and offer tax benefits if held to maturity. New issues have not been offered recently, but older bonds trade on the exchange.
A word of caution on “digital gold” offered by apps: it is convenient, but it is not regulated by SEBI, so check who actually stores the gold before putting in large amounts.
3. Buy in parts instead of all at once
Nobody can predict short-term gold prices. Instead of guessing the right day, spread your purchases over months through a SIP in a gold fund. You will buy more when prices dip and less when they spike, which smooths out your average cost.
4. Rebalance once a year
When gold has a great year, it can grow into a bigger share of your portfolio than you intended. Once a year, check your mix. If gold has gone well above your target, book some profit and move it to equity or debt. If it has fallen below, top it up. This simple habit makes you sell high and buy low without trying to time anything.
5. Do not forget tax and costs
Gold ETFs and funds have small expense ratios, and gains are taxed depending on how long you hold them. Physical gold has making charges and resale deductions. Before you buy, understand what you will actually take home when you sell. Tax rules change from time to time, so check the current rules or ask a tax adviser.
Common gold mistakes to avoid
- Buying a large amount at once because prices are “on fire”
- Treating jewellery as an investment
- Putting most of your savings in gold and missing equity growth
- Panic-selling during a short-term correction
The bottom line
Record gold prices are not a reason to rush in or stay away. Decide your allocation, buy steadily through ETFs or gold funds, and rebalance yearly. That way gold does its real job, protecting your savings, instead of becoming a source of stress. For more ways to protect your money, read 7 money moves that beat inflation.
This article is for general information only and is not investment advice. Please consider your own situation or consult a SEBI-registered adviser before investing.